An Intentionally Defective Grantor Trust (IDGT) is an irrevocable trust that can move appreciating assets and future growth outside a grantor's taxable estate while the grantor remains responsible for the trust's income taxes.
Key Takeaways
- An IDGT can move future appreciation outside the taxable estate.
- The grantor pays the trust’s income taxes, helping assets stay invested.
- An installment sale can freeze today’s value while shifting future growth.
- The trade-off: less estate-tax exposure may mean losing a basis step-up.
For families with significant wealth, successful estate planning often comes down to a deceptively simple objective: move future appreciation out of the taxable estate without unnecessarily giving up control, flexibility, or access to capital today.
An Intentionally Defective Grantor Trust, commonly known as an IDGT, is one strategy that can accomplish exactly that. Despite its peculiar name, an IDGT is not defective because something went wrong. The “defect” is intentional. The trust is deliberately structured to be treated differently under two separate parts of the tax code.
For estate and gift tax purposes, assets transferred to a properly structured IDGT can generally be removed from the grantor’s taxable estate. For income tax purposes, however, the grantor continues to be treated as the owner of the trust. That mismatch can create a powerful estate-planning opportunity for high-net-worth and ultra-high-net-worth families, particularly when the trust owns assets expected to appreciate substantially.
What Is an Intentionally Defective Grantor Trust?
An Intentionally Defective Grantor Trust is an irrevocable trust designed to remove assets from the grantor's estate while continuing to treat the grantor as the owner of those assets for federal income tax purposes.
The terminology can be confusing because an IDGT is “defective” only from the perspective of the income-tax rules. The trust is generally intended to be effective for estate-planning purposes. Once a completed gift is made to the trust, the transferred property and subsequent appreciation may be outside the grantor's taxable estate, assuming the trust has been properly drafted and administered.
At the same time, one or more provisions of the trust cause the grantor to remain the owner for federal income-tax purposes under the grantor-trust rules of Internal Revenue Code Sections 671 through 679. The IRS describes a grantor trust as one in which another person, generally the grantor, is treated as owning some or all of the trust's assets for income-tax purposes. This dual treatment is what gives the IDGT much of its planning power.
Why Would Someone Intentionally Create a “Defective” Trust?
The primary goal of an IDGT is generally to transfer appreciating assets to future generations while limiting the amount of future appreciation remaining in the grantor's taxable estate.
Consider a business owner with an interest currently valued at $10 million. If that interest grows to $30 million over the next 15 years and remains in the owner's estate, the entire $30 million may ultimately be subject to estate tax, depending on the owner's remaining exemption and estate-planning circumstances. If the $10 million interest is instead transferred to a properly structured IDGT, the subsequent $20 million of appreciation may occur outside the grantor's estate.
For wealthy families, removing future appreciation can be every bit as important as transferring today’s assets. That distinction is fundamental. Effective estate planning focuses not only on the amount of wealth that can be transferred today, but also on identifying the assets most likely to create significant future estate tax exposure if they continue to appreciate within the taxable estate. Those assets are often the strongest candidates for advanced gifting and wealth-transfer strategies.
The planning opportunity is not only the wealth transferred today. It is the future appreciation that may never enter the taxable estate.
How Does an IDGT Work?
An IDGT generally begins with the creation of an irrevocable trust for children, grandchildren, or other beneficiaries. The grantor then transfers assets to the trust, either through an outright gift, a sale, or a combination of the two. The trust agreement deliberately includes provisions that cause the trust to be classified as a grantor trust for income-tax purposes, without necessarily including the trust assets in the grantor's estate.
One commonly discussed provision is a power of substitution, sometimes called a swap power. Under IRC Section 675, certain administrative powers can cause grantor-trust treatment. One such provision permits the grantor, when appropriately structured, to reacquire trust property by substituting other property of equivalent value. The exact drafting matters enormously. An estate-planning attorney must ensure that the provision creates the desired income-tax result without creating unwanted estate-tax inclusion.
The IDGT's Most Powerful Feature: The Grantor Pays the Income Tax
Because the grantor is treated as the owner of an IDGT for income-tax purposes, the grantor generally reports the trust's taxable income on the grantor's individual income-tax return. At first glance, that may sound like a disadvantage. For affluent families, it can be one of the strategy's greatest benefits.
Suppose an IDGT owns an investment portfolio producing $500,000 of taxable income. The grantor may personally pay the federal and potentially state income taxes attributable to that income while the $500,000 remains in the trust. Economically, the grantor is reducing his or her own taxable estate while allowing the trust assets to remain invested for the beneficiaries.
Even better, the IRS has ruled that when the grantor is legally responsible for the tax attributable to a grantor trust, the grantor's payment of that income tax is not itself treated as an additional taxable gift to the trust beneficiaries. This can result in an additional wealth transfer each year without requiring the grantor to make another conventional gift. For sufficiently large trusts over long periods, this “tax burn” can become an important part of the estate-planning strategy.
When the grantor pays the income tax attributable to the IDGT, trust assets can remain invested for beneficiaries while the grantor's own estate is reduced by the tax payments.
Using an Installment Sale to an IDGT
One of the most sophisticated IDGT strategies involves selling appreciating property to the trust in exchange for a promissory note. Rather than gifting the entire asset to the trust and using a large portion of the gift and estate tax exemption, the grantor may first make a smaller seed gift to the trust and subsequently sell additional assets to it.
For example: A business owner has a closely held business interest worth $10 million. The owner establishes an IDGT and contributes sufficient seed capital. The owner then sells the $10 million business interest to the IDGT. In exchange, the trust gives the owner a $10 million promissory note carrying an appropriate interest rate. The trust pays principal and interest on the note over time. What happens economically? The $10 million value of the asset has effectively been “frozen” in the grantor's estate as the note.
If the business interest subsequently becomes worth $25 million, the additional $15 million of appreciation can potentially accrue inside the trust rather than inside the grantor's estate. The strategy works best when the growth of the transferred asset exceeds the cost of financing the installment note.
The IDGT Freeze: How Future Growth Escapes the Estate
A visual look at how an installment sale can lock in today's value while shifting tomorrow's appreciation outside the taxable estate.
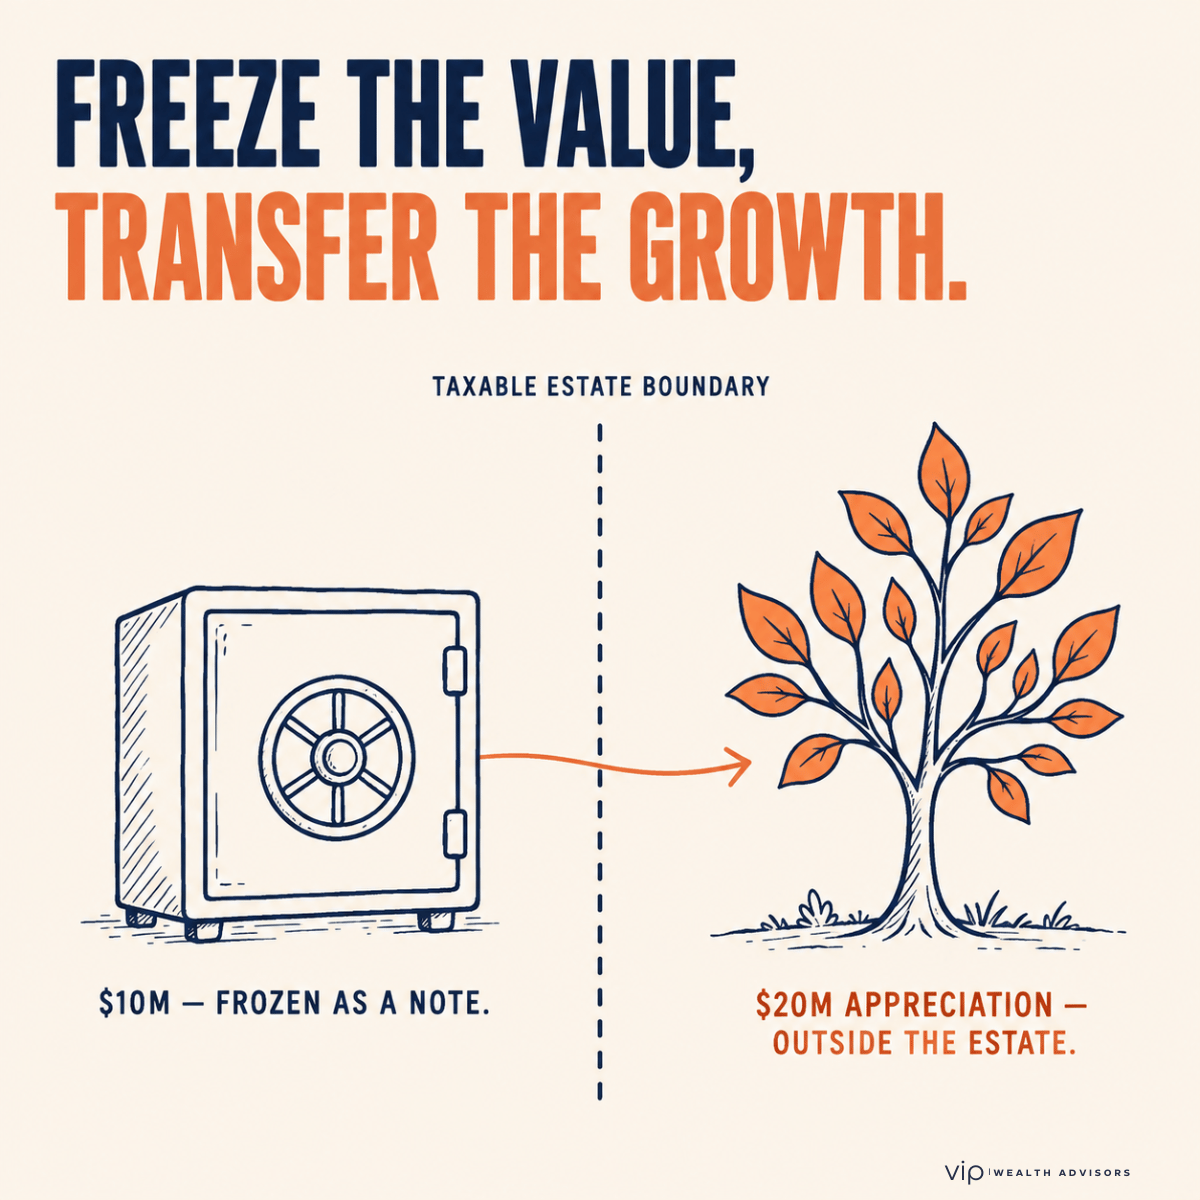
An installment-sale strategy is most effective when the transferred asset grows faster than the financing cost of the promissory note.
Does the Sale to an IDGT Trigger Capital Gains Tax?
Generally, a properly structured sale between a grantor and the grantor's IDGT is disregarded for federal income-tax purposes while grantor-trust status continues. The reasoning is unusual but important. For income-tax purposes, the grantor is treated as owning the trust assets. A transaction between the grantor and the grantor trust is therefore effectively treated as a transaction between the grantor and himself or herself.
Revenue Ruling 85-13 is foundational authority for this treatment. The IRS concluded in that ruling that because the grantor was treated as the owner of the trust, an exchange between the grantor and the trust did not constitute a recognized sale for federal income-tax purposes.
This means that a properly structured installment sale to an IDGT can potentially transfer a highly appreciated asset without immediately triggering the capital gain that an ordinary sale to an unrelated buyer might create. That is an exceptionally important distinction.
What Assets Work Well in an IDGT?
IDGTs tend to be most powerful when funded with assets that have substantial expected appreciation.
Possible candidates include:
- Interests in closely held businesses
- Pre-IPO or founder stock
- Concentrated equity positions
- Family limited partnership interests
- LLC interests
- Certain investment portfolios
- Income-producing real estate
- Development property
- Private equity interests
- Other assets expected to appreciate substantially
An asset generating strong cash flow may be particularly useful in an installment-sale strategy because the trust needs liquidity to service its promissory note. Asset selection should not be based solely on expected return, however. Income-tax basis, valuation, liquidity, cash flow, concentration risk, control rights, and the family's overall estate plan all matter.
IDGTs and the 2026 Estate Tax Exemption
The federal basic exclusion amount is $15 million per individual for 2026. That means some families who previously expected to face an immediate federal estate tax problem may now have additional room for planning. But a larger exemption does not make estate planning irrelevant. A family worth $20 million today could be worth considerably more 15 or 20 years from now.
Likewise, someone with a rapidly growing business, concentrated stock position, private-company equity, or appreciating real estate may eventually accumulate an estate well beyond the available exemption.
An IDGT can therefore be viewed not merely as a way to transfer existing wealth, but as a way to redirect future growth before it occurs. That is often where the greatest leverage exists.
The Basis Problem: Estate Tax Savings Can Come at a Cost
There is an important counterweight to the estate-tax benefits of an IDGT. Assets successfully removed from the grantor's taxable estate generally do not automatically receive a new income-tax basis equal to their fair market value upon the grantor’s death.
The IRS addressed this directly in Revenue Ruling 2023-2. It concluded that property held in an irrevocable grantor trust that is not included in the grantor's gross estate does not receive a basis adjustment under IRC Section 1014 merely because the grantor was treated as the trust's owner for income-tax purposes.
This creates one of the central trade-offs in advanced estate planning: Is it more valuable to remove the asset from the estate, or to retain it and potentially receive a step-up in basis at death? The answer depends on the numbers.
The Central Trade-Off: Estate Tax Savings vs. a Basis Step-Up
Removing an asset from the estate and keeping it for a step-up in basis both have real value — the right answer depends on the numbers.
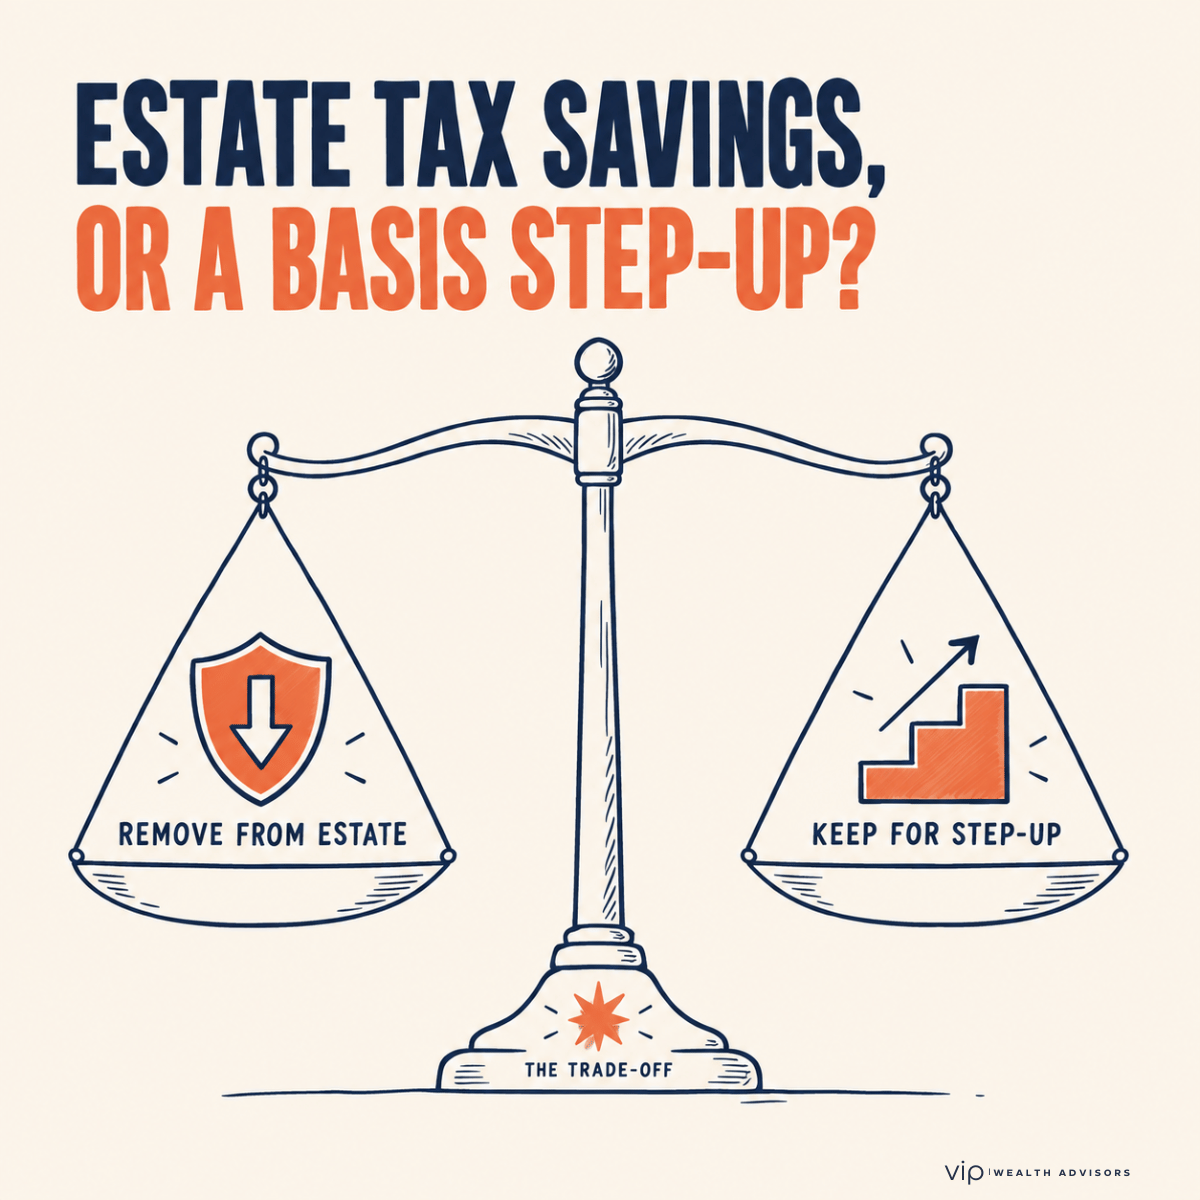
For a family clearly exposed to substantial estate tax, removing decades of future appreciation may dramatically outweigh the potential capital-gains benefit of a basis adjustment. For someone with little or no likely estate-tax exposure, giving away a highly appreciated, low-basis asset could potentially create unnecessary future capital-gains taxes. This is why IDGT planning should integrate estate-tax planning and income-tax planning, rather than treating them as separate exercises.
Moving appreciation outside the estate can reduce future estate-tax exposure, but assets outside the estate may give up a valuable basis adjustment at death. Both sides of the tax equation need to be modeled together.
Using a Swap Power for Basis Management
The grantor's power to substitute assets of equivalent value can potentially provide another planning opportunity. Imagine an IDGT owns stock worth $5 million with a basis of only $500,000. The grantor personally owns $5 million of cash or securities with very little embedded gain. Subject to the trust terms and applicable law, the grantor may potentially substitute $5 million of high-basis assets for the $5 million of low-basis stock held by the trust. The low-basis stock would return to the grantor.
If that stock is later included in the grantor's taxable estate, it may potentially qualify for a basis adjustment under Section 1014 at death. The trust would instead hold the high-basis assets. This type of planning illustrates why an IDGT should not simply be established and forgotten. The trust and the grantor's balance sheet should be reviewed periodically as asset values, tax basis, tax laws, health, family circumstances, and estate-tax exposure change.
What Happens to an IDGT When the Grantor Dies?
An IDGT does not necessarily terminate upon the grantor's death. Instead, the grantor-trust status attributable to the deceased grantor generally ends. The trust may then continue as a separate nongrantor trust for children, grandchildren, or future generations depending upon its governing document. The income-tax consequences of terminating grantor-trust status can be complex, particularly when outstanding debts, installment obligations, partnerships, or other sophisticated assets are involved. The trust's post-death administration should therefore be coordinated among the estate-planning attorney, tax professional, trustee, and financial advisor.
IDGT vs. GRAT: What's the Difference?
Both IDGTs and Grantor Retained Annuity Trusts can be used to transfer future appreciation, but their mechanics differ. A GRAT involves transferring assets to a trust while the grantor retains a specified annuity interest for a defined period. An IDGT installment-sale strategy generally involves transferring assets to a trust in exchange for a promissory note.
GRATs can be attractive when the grantor wants to transfer appreciation above the applicable Section 7520 hurdle rate while using little taxable gift exemption. IDGTs can offer greater long-term flexibility and can be particularly attractive when the objective is to establish a multigenerational trust and transfer substantial appreciating assets. Neither strategy is inherently better. They solve different planning problems.
IDGT vs. SLAT: What's the Difference?
A Spousal Lifetime Access Trust, or SLAT, is generally designed to remove assets from one spouse's estate while permitting the other spouse to remain a beneficiary of the trust. An IDGT describes the trust's income-tax treatment rather than its beneficiaries. In fact, a SLAT can itself be structured as a grantor trust. This means the two concepts are not mutually exclusive. A trust might simultaneously be:
- irrevocable,
- outside the grantor's taxable estate,
- a grantor trust for income-tax purposes, and
- a SLAT because the grantor's spouse is a beneficiary.
The terminology describes different characteristics of the same trust structure.
What Are the Risks of an IDGT?
IDGTs can be extraordinarily useful, but they are not appropriate for everyone. Important considerations include:
- Loss of direct ownership. Assets transferred through completed gifts generally belong to the trust, not the grantor.
- Gift tax exemption usage. Seed gifts and other transfers may consume available lifetime exemption.
- Valuation risk. Closely held businesses, real estate, LLC interests, and similar assets may require qualified appraisals.
- Liquidity. An installment-sale strategy requires the trust to make note payments.
- Income-tax burden. The grantor may face significant income taxes attributable to trust assets.
- Basis considerations. Assets outside the estate may miss a valuable basis adjustment at death.
- Administrative complexity. Trust accounting, tax reporting, valuations, note payments, and legal administration must be handled correctly.
- Changing tax laws. Estate, gift, GST, and income-tax laws can change over the many decades an irrevocable trust may exist.
An IDGT should therefore be implemented as part of a coordinated estate and financial plan, not as an isolated tax transaction.
An IDGT is not a stand-alone tax move. The trust, valuation, note terms, liquidity, income-tax burden, estate plan, and ongoing administration all need to work together.
Estate Planning Is About More Than Today's Estate Value
One of the biggest mistakes families can make is evaluating estate-tax exposure based solely on current net worth. A $15 million or $20 million estate today can become dramatically larger over the next several decades. A closely held business can multiply in value. Private-company equity can experience a liquidity event. Real estate can appreciate. Investment portfolios can compound.
An Intentionally Defective Grantor Trust can provide a powerful way to move some of that future growth outside the taxable estate before it occurs. But the most effective IDGT planning goes well beyond simply transferring assets.
A thoughtful strategy should account for the grantor’s remaining exemption, projected estate growth, income-tax basis, expected returns, valuation opportunities, liquidity needs, cash flow, potential capital-gains exposure, generation-skipping planning, and the family’s long-term objectives. The goal is to identify the right assets, transfer them at the right time, and structure the transaction so that the potential estate-tax benefits meaningfully outweigh the income-tax, administrative, and planning trade-offs.
For high-net-worth families, an IDGT can become an important part of a broader wealth-transfer strategy, particularly when significant appreciation is expected. When coordinated carefully with the family’s estate plan, tax strategy, and investment planning, it can help preserve more wealth for future generations while providing greater control over how and when that wealth is transferred.
Frequently Asked Questions About Intentionally Defective Grantor Trusts
What does IDGT stand for?
IDGT stands for Intentionally Defective Grantor Trust. It is an irrevocable trust designed so that assets can generally be excluded from the grantor's estate for estate-tax purposes, while the grantor remains responsible for the trust's income taxes.
Why is an IDGT called “defective”?
An IDGT is called defective because it intentionally violates, or triggers, certain grantor-trust rules for income-tax purposes. The defect is deliberate and does not mean the trust was drafted incorrectly.
Is an IDGT irrevocable?
Yes, an IDGT used for estate planning is generally irrevocable. The irrevocable structure is essential to achieving the intended transfer-tax objectives.
Who pays the taxes on an IDGT?
The grantor generally pays the income tax generated by an IDGT while grantor-trust status remains in effect. This allows the trust assets to continue compounding without being reduced by those income-tax payments.
Is paying an IDGT's income tax considered another gift?
Generally, no. The IRS has ruled that a grantor's payment of income tax attributable to a grantor trust is not a gift to the beneficiaries when the grantor is legally responsible for that tax.
Are IDGT assets included in the grantor's estate?
Properly transferred IDGT assets can generally be excluded from the grantor's taxable estate. However, the trust must be drafted and administered carefully so that retained rights do not trigger estate inclusion.
Does an IDGT receive a step-up in basis at death?
Not automatically. The IRS has concluded that assets in an irrevocable grantor trust that are not included in the grantor's gross estate generally do not receive a Section 1014 basis adjustment solely because the trust was a grantor trust.
Can you sell assets to an IDGT?
Yes. Selling appreciating assets to an IDGT in exchange for a promissory note is a common advanced estate-planning strategy. The objective is generally to freeze the value at the time of transfer while shifting future appreciation to the trust.
Does selling property to an IDGT trigger capital gains tax?
A sale between a grantor and a grantor trust is generally disregarded for federal income tax purposes, and the grantor is treated as the owner of the trust. Revenue Ruling 85-13 provides important authority underlying this treatment.
What is a seed gift to an IDGT?
A seed gift is an initial contribution of assets to an IDGT intended to provide the trust with economic substance and financial capacity before an installment sale. The appropriate amount depends on the transaction and should be determined with qualified estate-planning counsel.
What assets are best for an IDGT?
Assets with strong appreciation potential are often the best IDGT candidates. These may include closely held business interests, private-company shares, investment real estate, partnership interests, concentrated securities, and other assets expected to appreciate substantially.
Can an IDGT own real estate?
Yes. An IDGT can own real estate, including investment or income-producing property, assuming the ownership structure and financing arrangements are appropriate.
Can an IDGT own a family business?
Yes. Closely held business interests are frequently considered for IDGT planning because transferring the business before substantial future appreciation can potentially shift that growth outside the owner's taxable estate.
Can an IDGT own S corporation stock?
Potentially, yes, but S corporation shareholder eligibility rules must be carefully considered. Certain grantor trusts can qualify as eligible S corporation shareholders, and additional elections may become necessary after grantor-trust status ends.
Can the grantor take assets back from an IDGT?
The grantor generally cannot simply withdraw gifted assets at will. However, some IDGTs include a carefully drafted substitution power permitting the grantor to exchange assets with the trust for property of equivalent value.
What is the purpose of the swap power in an IDGT?
A swap power can help create grantor-trust status and may provide valuable basis-management flexibility. For example, a grantor may potentially substitute high-basis property for low-basis appreciated assets held inside the trust. IRC Section 675 specifically addresses a power to reacquire trust corpus by substituting property of equivalent value.
Can an IDGT be a dynasty trust?
Yes. An IDGT can potentially be structured as a long-term or dynasty trust for children, grandchildren, and future generations. Generation-skipping transfer tax planning becomes particularly important when designing a multigenerational structure.
What happens to an IDGT after the grantor dies?
The trust can continue after the grantor's death according to its governing document. Grantor-trust status attributable to the deceased grantor generally ends, and the trust may thereafter operate as a separate nongrantor trust.
What is the difference between an IDGT and a revocable living trust?
A revocable living trust generally remains part of the grantor's taxable estate and is primarily used for probate avoidance and estate administration. An IDGT is irrevocable and is generally designed to transfer wealth outside the grantor's estate.
Both may be grantor trusts for income-tax purposes, but their estate-planning purposes are fundamentally different.
How much money do you need for an IDGT?
There is no statutory minimum net worth required to establish an IDGT. In practice, however, the legal, appraisal, administrative, and tax complexity means the strategy tends to be most useful for families with substantial wealth or assets expected to appreciate significantly.
When should someone consider an IDGT?
An IDGT may be worth evaluating when an individual or family:
- Has significant current or projected estate-tax exposure
- Owns a rapidly appreciating business
- Holds private-company or pre-IPO stock
- Owns appreciating real estate
- Wants to transfer wealth to children or grandchildren
- Wants to shift future appreciation outside the estate
- Has sufficient liquidity to continue paying income taxes attributable to trust assets
- Wants to establish a long-term multigenerational estate plan
Is an IDGT right for every wealthy family?
No. An IDGT is a specialized estate-planning strategy, and its benefits depend heavily on expected asset appreciation, income-tax basis, estate-tax exposure, cash flow, liquidity, family objectives, and the structure of the transaction.
For some families, an IDGT can transfer tremendous amounts of future wealth.
For others, retaining assets personally and preserving the possibility of a basis adjustment may produce the better result.
Could an IDGT Fit Your Family's Wealth-Transfer Plan?
An IDGT can be powerful when significant appreciation is expected, but the estate-tax benefit needs to be weighed against basis, liquidity, cash-flow, valuation, and administrative trade-offs. A coordinated analysis can help determine whether the strategy fits your assets and long-term goals.